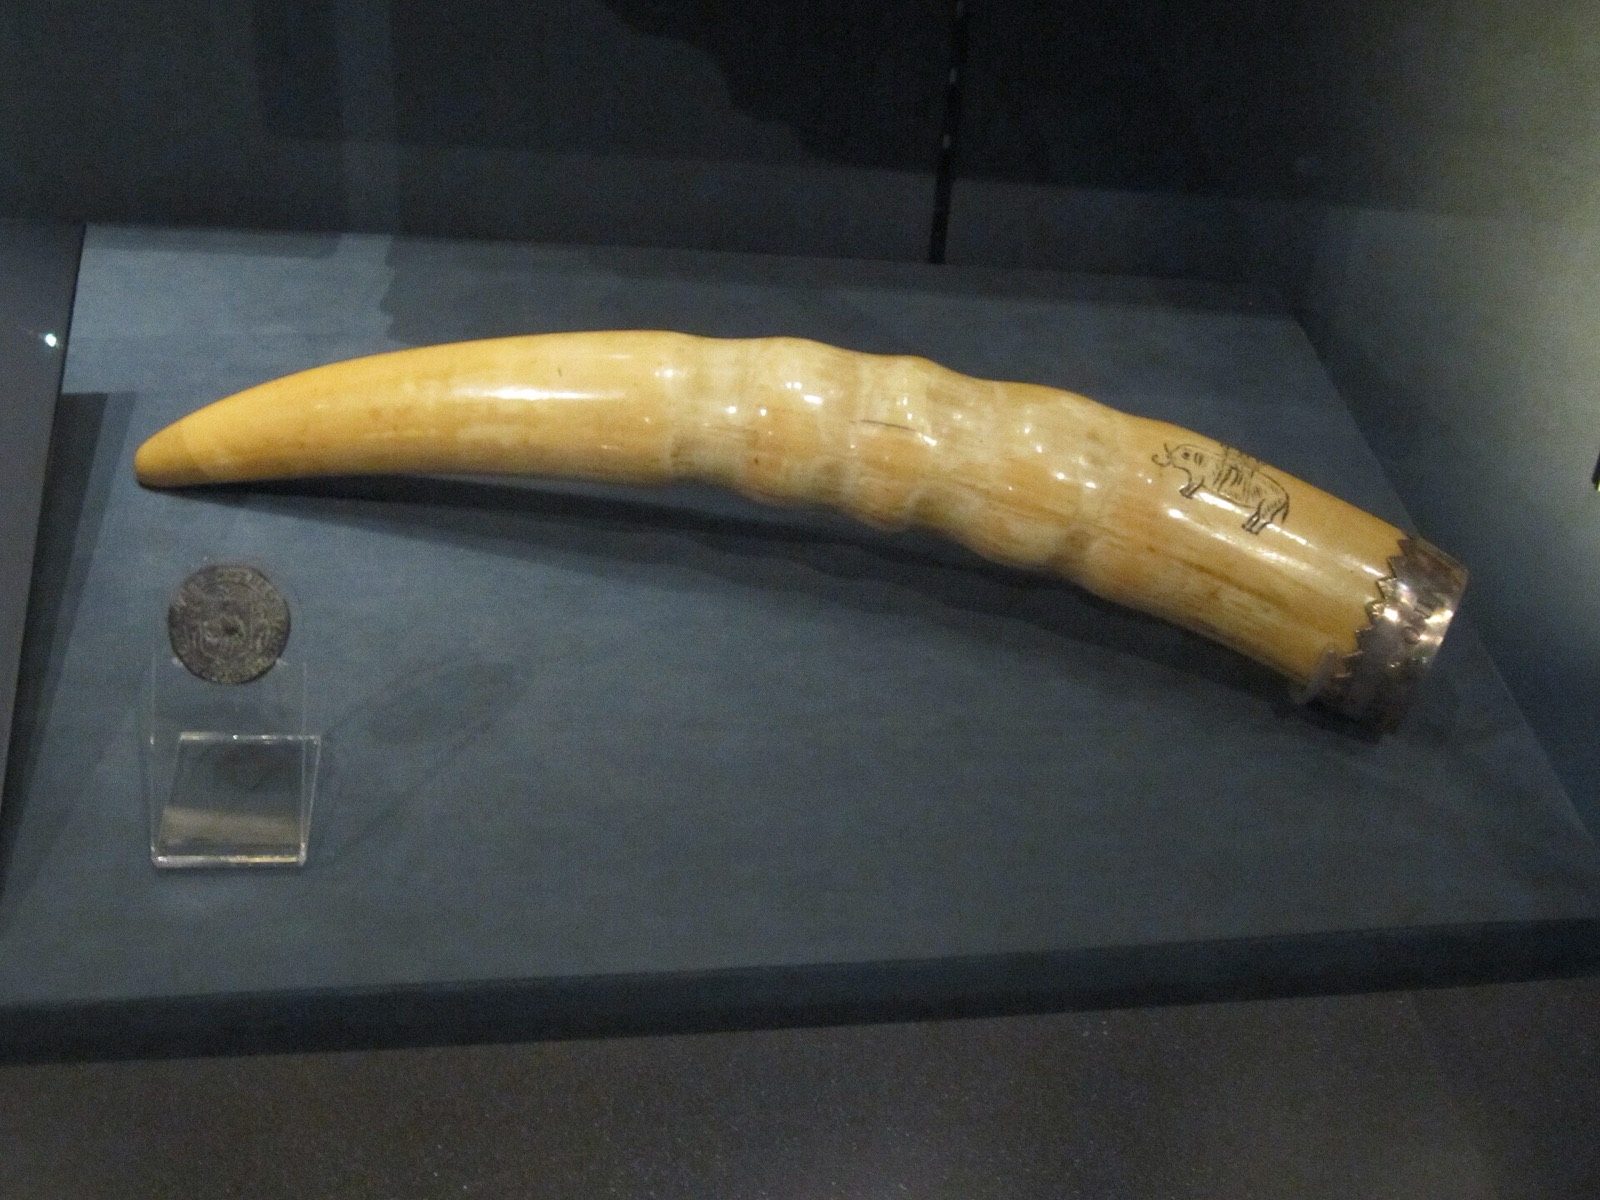
Ivory marked by the Royal African Company. International Slavery Museum, Liverpool. Wikimedia Commons.
The Revenue Act of 1964 cut federal income tax rates on households and on corporations, and wage earners who owed the tax saw it as more money in the paycheck.
A stretched household that earned too little to owe income tax saw little or no gain in take-home pay from a cut in rates it was not paying.
A household that did owe the tax received a larger net wage when the withholding tables changed, with no change in the job itself.
A profitable corporation kept a larger share of its earnings, and nothing in the statute required it to hire, to invest, or to raise a wage with the difference.
John Kennedy had proposed the cut, and Lyndon Johnson signed it, as a deliberate use of the budget to lift private spending.
For people inside the income tax, the Treasury withheld less, and the act brought the top rate on individual income down from 91 percent to 70 percent in steps.
People below the tax, often the poorest wage earners, needed a different policy if the goal was their budget, because a rate cut cannot give back a tax that was never taken.
Revenue Act of 1964