The Fed held rates in June while energy inflation stayed elevated
The central bank kept its benchmark rate at 3.5 to 3.75 percent, describing growth as solid while noting uncertainty from the Middle East conflict.
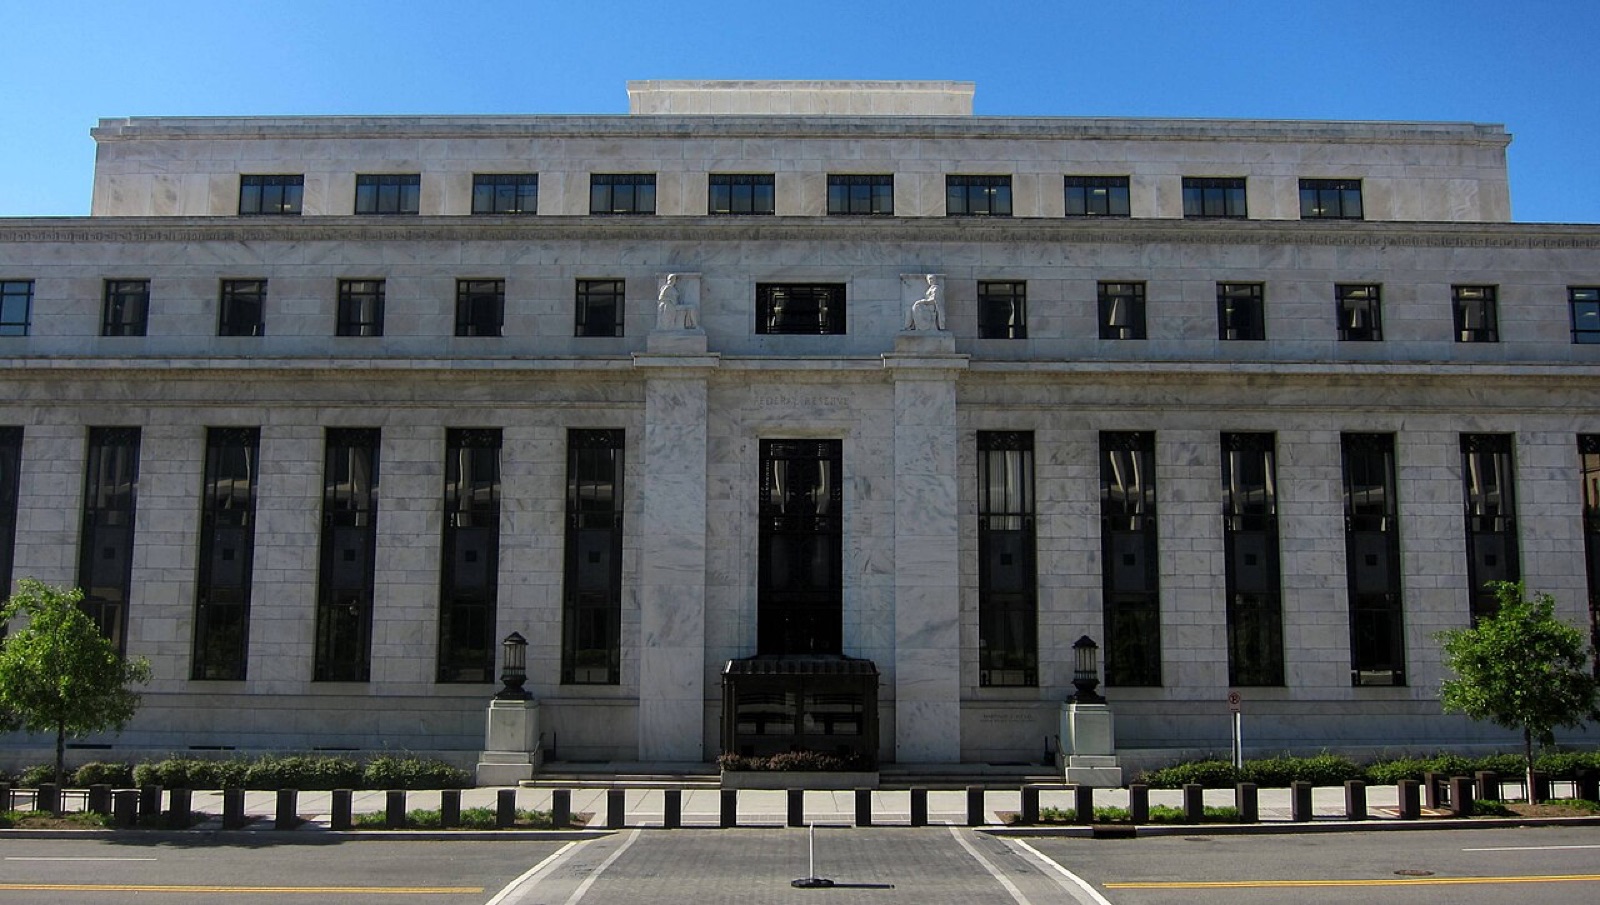
Published October 27, 2026. This retrospective examines the Federal Reserve’s June 17, 2026 decision.
The Federal Reserve left its benchmark interest-rate range at 3.5 to 3.75 percent on June 17. The decision was unanimous. Officials said economic activity was expanding at a solid pace, while inflation remained above the Fed’s 2 percent goal and energy supply shocks were contributing to price increases.
What the benchmark rate does
The federal funds rate is the overnight rate banks charge one another for certain loans. The Fed sets a target range to influence financial conditions. It does not directly set every mortgage, auto loan or credit-card rate. Banks and lenders also consider market rates, borrower risk, funding costs and competition.
A policy hold means the central bank chose not to change that target at this meeting. It does not mean borrowing became cheap or that existing loan payments automatically changed. Credit cards with variable rates may move with benchmark rates over time, while fixed-rate mortgages generally do not reset just because the Fed meets.
The problem with a supply shock
Higher energy costs can raise inflation while also reducing the money households and businesses have for other purchases. Raising interest rates cannot create more oil or reopen a shipping route. It can cool demand and limit broader price pressure, but that cooling can weigh on hiring, home purchases and business investment.
That conflict shaped the Fed’s language. The committee acknowledged elevated uncertainty tied in part to the Middle East and said inflation was above its goal. It also described job gains as keeping pace with the workforce. Officials were weighing a price problem whose source was partly outside the usual levers of monetary policy.
Projections are not promises
The Fed’s June economic projections summarized individual officials’ views of likely growth, unemployment and inflation under what each considered appropriate policy. They were not a collective guarantee. Projections change when new data or shocks arrive, and the committee’s actual decisions are made meeting by meeting.
For a family deciding whether to borrow, the hold meant the benchmark stayed where it was for the moment. It did not promise a near-term cut. The energy shock and later inflation reports would continue to shape expectations. WallPost’s September rate story documents a subsequent increase as a separate decision, rather than folding the two meetings into one continuous event.
The committee’s statement also reflected its two-part mandate: maximum employment and stable prices. In practical terms, officials must judge whether inflation is likely to remain too high and whether tighter credit could cause unnecessary job losses. Neither goal can be evaluated from one data release. That is why a hold communicates caution about the outlook, not a claim that the economy has no problems.
The June decision came before later reports showed the full summer pattern. A central bank works with the information available at each meeting. It cannot respond to data that have not yet been published. Looking back, readers can see subsequent inflation and employment figures, but they should not judge the June committee as if it had already seen them. The contemporaneous statement is the clearest record of its reasoning.
Sources
Spotted an error? Tell the editor. Corrections are logged on our corrections page.